Find A Better Rate
Free RP Data Reports
Open menu

First home buyer support

First home buyer loans, with personal broker support

Compare first home buyer loans with Chris Berry, your Melbourne-based mortgage broker. Understand suitable options from a panel of more than 40 lenders, including rates, fees, features and deposit requirements. Get personal help with your application through to settlement, with phone and video appointments available Australia-wide.

No broker fees · 18+ years of lending experience

Prefer to speak now? Call 03 9125 4339

Home loan enquiry

Request a callback

Leave your contact details and Chris will get in touch about your first home. No appointment time or financial documents needed.

Add a question or preferred call time (optional)

By submitting, you agree that Find A Better Rate may contact you about this request. Your details are handled in accordance with our privacy policy.

Your options

How our first home buyer broker service helps you

Buying your first home involves more than finding an interest rate. Chris helps you turn your savings, income and property goals into a practical lending plan, explains the trade-offs and supports your application.

Understand your buying position

Review your income, expenses, debts and savings with Chris. Work through a comfortable repayment range, deposit, buying costs and a buffer before setting your property budget.

Compare suitable lender options

Chris compares lender policies, rates, fees and features across our panel of more than 40 lenders. You can discuss the reasons for a recommendation and assistance that may be relevant to your circumstances.

Get help through settlement

Get guidance on application documents, pre-approval conditions and lender requests. Chris helps coordinate the finance process with your lender and conveyancer as you move towards settlement.

Compare your first home loan

How to compare first home buyer loans

Your first mortgage should fit your budget as well as the home you want to buy. Chris compares suitable options from our lender panel and explains how the costs, features and lending requirements apply to you. Our panel does not include every lender or home loan in Australia.

A first home buyer loan is a home loan used to purchase your first property. It does not need to carry a special first-home-buyer label. The useful comparison is how each available loan fits your budget, deposit and plans.

Rates and repayments

Compare fixed, variable and split-rate options. Check repayments using the same loan amount and term, and consider whether your budget could manage higher rates.

Fees and comparison rates

Look at application, ongoing and package fees alongside the interest rate. A comparison rate includes most fees, but its assumptions may differ from your loan and it does not capture every cost.

Features you will use

Ask about offset accounts, redraw and extra repayments. Check the access rules, limits and fees before paying for features that may not suit how you manage money.

Deposit and lender requirements

Your savings, income, expenses, credit history and chosen property affect which loans may be available. Include purchase costs in your budget as well as the deposit.

Fixed, variable or split: which loan structure fits?

Variable rate

Repayments can change when the rate changes. Compare flexibility for extra repayments and any offset or redraw features, including their fees and conditions.

Fixed rate

The rate stays fixed for an agreed period. Check extra-repayment limits and possible break costs if you repay or switch early, as well as the rate after the fixed period ends.

Split loan

Part of the loan is fixed and part variable. This combines some repayment certainty with flexibility; compare the costs and conditions applying to each portion.

Ask Chris for a comparison based on your proposed loan amount, deposit and repayment needs. Rates and eligibility can change; a personalised comparison is more useful than assuming one advertised rate is available to every buyer.

Discuss your first home loan options with Chris

Start with our first home buyer deposit guide, explore Australian government assistance, and use the pre-approval guide to prepare for a lender assessment.

Buying in Victoria? Check the first home buyer stamp duty exemption and concession rules, then build a budget for your other purchasing costs. Bring your savings, income details and target property price to our discussion so we can review the full buying plan.

For independent guidance, read ASIC’s Moneysmart guide to choosing a home loan.

Buying your first home in Melbourne: start with the finance questions

Whether you are looking at an apartment, townhouse or house, bring the property price and your savings to the first conversation. Chris can help distinguish the amount a lender may approve from the repayments you would be comfortable making.

  • Before inspecting: review your home loan borrowing power, deposit and purchase costs.
  • Before making an offer: understand pre-approval conditions and ask your conveyancer about the contract and any finance clause.
  • Before bidding at auction: arrange legal advice and confirm the finance position. Conditional pre-approval is not an assurance that the chosen property will receive final approval.
  • Before settlement: confirm the lender’s outstanding requirements, cash contribution and insurance arrangements.

For a Victorian purchase, estimate stamp duty separately from the deposit. Government assistance and lender approval involve separate eligibility checks.

Bring what you have, even if you are still saving

Start with income figures, savings, regular expenses, debt balances and credit limits. If you have chosen a property, bring its listing and your proposed timing. Chris will explain which supporting records are needed next. Avoid sending identity or financial documents through the general enquiry form.

Book your first home buyer appointment or learn more about our Melbourne mortgage broker service.
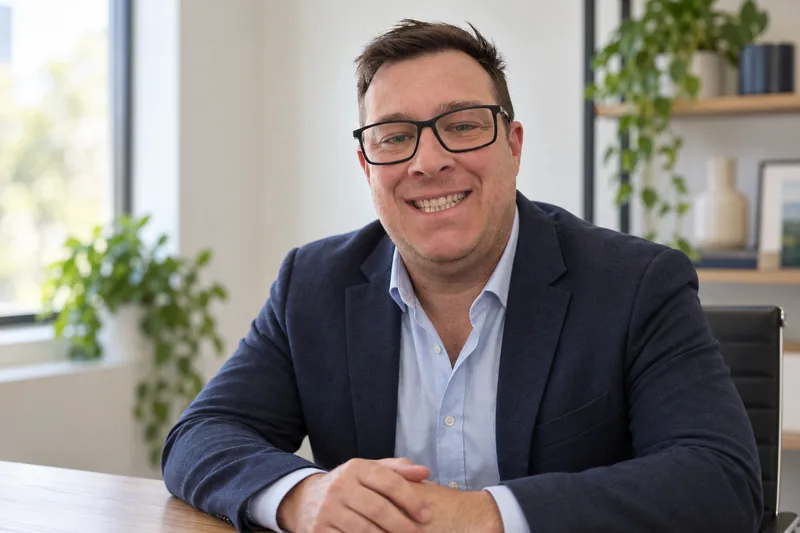
Chris Berry, owner and mortgage broker at Find A Better Rate

Meet your broker

Work with Chris Berry on your first home loan

Chris is the owner and mortgage broker behind Find A Better Rate, with more than 18 years of experience across home lending. Based in Melbourne, he helps first home buyers understand lender requirements and make informed decisions about their finance.

Bring your questions, even if you are still saving or unsure where to start. Chris can help identify the preparation steps that matter for your circumstances, explain your options in plain language and support you through the lending process.

More about Chris Berry

Client experiences

Trusted by home buyers and homeowners.

4.9from 52 Google reviews
Read all Google reviews
“Thanks Chris for a good experience and also for saving me lots of money.”

Jenna Seymour

Google review

“Thank you SO much for everything, couldn't be happier with the outcome :)”

Erica Dowlzak

Google review

“Would highly recommend his services.”

Pieter Molenaar

Google review

Fees explained

No broker fees for first home buyers

Find A Better Rate does not charge first home buyers a broker fee. We are paid commission by the lender when your home loan settles, and Chris will explain the remuneration arrangements before you proceed.

Lender fees and property-buying costs may still apply. We help you consider these separately from our broker service, including loan fees, conveyancing and any applicable stamp duty or lenders mortgage insurance.

How it works

From your first conversation to settlement

  1. 01

    Start with a free conversation. Discuss your savings, income, debts, target property price and preferred repayments. Chris helps identify your next preparation steps.

  2. 02

    Compare and prepare. Review suitable lenders and potential assistance, gather supporting documents and prepare for pre-approval. Understand its conditions before making a commitment.

  3. 03

    Move towards settlement. Chris helps with lender requests and finance deadlines, coordinating with your lender and conveyancer. You can also discuss your loan needs after settlement.

Common questions

First home buyer loans and broker FAQs

What does a first home buyer broker do?

Chris reviews your financial position, compares suitable home loans from our lender panel and explains the reasons behind a recommendation. He helps prepare your application, responds to lender requirements and supports the finance process through to settlement. Our panel does not include every lender or home loan in Australia.

What happens at my first appointment?

The first appointment is a free conversation about your plans, savings, income, existing debts and repayment budget. Have approximate figures and your questions ready; you do not need to have chosen a property. Chris can explain what information will be needed next and help you identify practical preparation steps.

Which mortgage loans are suitable for first-time home buyers?

There is no single loan that suits every first home buyer. Chris can compare fixed, variable and split-rate options against your deposit, repayment budget and need for flexibility. The recommendation depends on your circumstances and lender requirements, rather than whether a loan is marketed specifically to first home buyers.

How much deposit do I need for my first home loan?

The amount depends on the lender, property and any assistance you qualify for. Some buyers may be eligible for a smaller-deposit pathway. Borrowing with less than a 20% deposit can involve lenders mortgage insurance unless an exemption or eligible scheme applies. Allow for buying costs separately and check the total funds required before committing.

What do Australian lenders check when assessing a first home buyer?

Lenders consider your income, employment, regular expenses, existing debts, credit history, savings and the property offered as security. Having a deposit or qualifying for government assistance does not guarantee loan approval. Chris can help compare lender requirements and identify preparation steps before you apply.

What documents should I prepare for my first mortgage application?

Start with identification, recent payslips or other income evidence, savings and bank statements, and details of debts and living expenses. Self-employed applicants may need tax returns and business financial records. Requirements vary, so Chris will help you prepare a checklist for your circumstances and proposed lender.

Should I get pre-approval before making an offer?

Pre-approval can help clarify your likely borrowing position before you make an offer, but it is conditional and can expire. Final approval can depend on the property, valuation and further checks. Understand any finance conditions and seek advice about your contract before committing to a purchase.

When should a first home buyer speak with a mortgage broker?

Speaking early can help you understand your likely budget, deposit position, purchasing costs and preparation steps before you become committed to a property.

How much does a mortgage broker cost a first home buyer?

Find A Better Rate charges first home buyers no broker fees. We are paid commission by the lender when your home loan settles. Chris will explain the remuneration arrangements before you proceed. Lender fees and property-buying costs may still apply and are separate from our broker service.

Can a broker help with government first home buyer schemes?

A broker can help identify lending pathways and participating lenders that may be relevant. Eligibility is determined under the applicable program and lender rules.

Does using a broker guarantee approval?

No. Every lender assesses the application under its credit criteria. A broker can help prepare, compare and present the application, but cannot guarantee a lender decision.

Ready when you are

Let’s find your better rate.

Book a free 30-minute appointment with a mortgage broker to clarify your next step.